All Categories
Featured
A bipartisan group of legislators has introduced legislation to punish deceptive practices used by deceptive credit repair organizations.The Ending Scam Credit Repair Act, or ESCRA, by Sens. Chris Coons( D-Del. )and Lisa Murkowski( R-Alaska) would enhance protections for consumers by restricting credit repair organizations from gathering payment till six months after they have actually offered evidence that a customer's credit report has enhanced, according to the sponsors. A buddy bill( H.R. 306) was introduced in your house by Reps. Sarah McBride( D-Del.) and Young Kim( R-Calif. ). In a declaration in support of the legislation, Kirsten Sutton, EVP of congressional relations and legal affairs at the American Bankers Association, kept in mind that banks help customers build credit through transparent products, financial education and long-lasting support, "and this essential legislation reinforces those responsible paths by targeting deceptive credit repair work plans."" ABA has actually regularly supported efforts to reinforce consumer self-confidence in the credit system, and we praise Senators Coons and Murkowski, and Representatives McBride and Kim, for their management in working to make sure consumers are protected, "Sutton stated. The project will gear up both consumers and bank volunteers with reliable details, practical tools and expert insights, including recommendations on how to identify deceptive credit repair work companies.( Short Article Updated Jan. 6 and 8, 2026) This short article lists federal and state consumer law modifications set up to go into effect or expire during the period from December 1, 2025, through January 1, 2027. Other consumer law changes will be enacted in 2026 and will enter into result in 2026; this article notes modifications whose reliable dates have actually already been scheduled as of December 31, 2025. NCLC motivates readers to send( to) additional consumer law changes reliable in 2026, specifically modifications in state consumer legislation. NCLC will include appropriate submissions to this short article. Essential amendments to Personal bankruptcy Guideline 3002.1 and 6 associated new personal bankruptcy types went into effect on December 1, 2025. The modifications safeguard homeowners who utilize chapter 13 bankruptcies to ward off foreclosures and keep themselves existing on their home mortgages, providing them information required to effectively finish a treatment plan and emerge from chapter 13 without surprise, undisclosed costs, or payment quantities due. New Guideline 8006( g) will clarify that any celebration to an appeal might file a request that a court of appeals authorize a direct appeal. 26 U.S.C. 108( a) provides that certain forgiveness on a home mortgage loan is not considered earnings for earnings tax purposes, however the Qualified Principal Residence Insolvency Exclusion from Income expired at the end of 2025. Although other exemptions from taxability of forgiven financial obligation might apply, this exemption no longer applies. The American Rescue Strategy Act momentarily got rid of federal earnings tax consequences for all federal student loan discharges and cancellations that took place in between January 1, 2021, and December 31, 2025. See. This exclusion has actually not been extended, and the amounts released or cancelled from federal student loans beginning on January 1, 2026, may count towards gross income unless another exclusion applies. See( Dec. 15, 2025 ). This exemption does not apply to home-secured credit or trainee loans. See. On January 1, the adjusted total loan quantity threshold for high-cost mortgages increases from $26,968 to$ 27,592, and the adjusted points and fees dollar trigger for high-cost home mortgages increases from$ 1,348 to $1,380. 15, 2025 ). See likewise. To figure out whether a covered transaction is a competent home loan( QM), the overall points and fees charged might not surpass the threshold set for the size of the loan. Effective January 1, 2026, these limits increase. For QMs under the basic QM loan definition in 12 C.F.R. For all categories of QMs, the thresholds for total points and costs in 2026 will be 3% of the overall loan quantity for a loan greater than or equal to$ 137,958;$ 4,139 for a loan amount higher than or equivalent to$ 82,775 however less than$ 137,958 ; 5% of the overall loan quantity for a loan greater than or equivalent to$ 27,592 but less than$ 82,775;$ 1,380 for a loan amount greater than or equal to $17,245 however less than $27,592; and 8% of the total loan quantity for a loan amount less than $17,245. 15, 2025 ). See usually. Effective January 1, the exemption threshold for special appraisal requirements for "higher-risk mortgages "increases from $33,500 to $ 34,200. See (Dec. 16, 2025). See. Reality in Loaning Reg. Z, 12 C.F.R. 1026.6 (b) (2)( iii )and 1026.60( b)( 3) need financial institutions to disclose any minimum interest charge surpassing $1.00 that might be imposed during a billing cycle. 7, 2026). Efficient January 1, 2026, banks, savings associations, and cooperative credit union with assets of $59 million or less as of Dec. 31, 2025, are exempt from gathering information in 2025( the old threshold was $58 million ).( Jan. 7, 2026). The CRA possession thresholds for particular exemptions are increased since January 1, 2026, so that "small bank "indicates a bank that, since December 31 of either of the prior two calendar years, had assets of less than$ 1.649 billion. See( Jan. 7, 2026). Reliable January 1, 2026, the maximum charge to a consumer under the FCRA for file disclosure is$ 16.00, up from$ 15.50. (Dec. 15, 2025 ). Customers are likewise entitled to certain complimentary disclosures, including free weekly file disclosures from Equifax, Experian, and TransUnion. See. On January 1, 2026, the Consumer Leasing Act exemption for consumer leases exceeding a total legal commitment amount is increased from$ 71,900 to$ 73,400. 15, 2025). See. FHA has revealed new loan limitations for 2026. The single-family, low-cost-area ceiling increases to $541,287 and the high-cost-area ceiling increases to$ 1,249,125. See( Dec. 11, 2025). For HECM reverse home mortgages the maximum claim amount increases on January 1 to $1,249,125. See (Dec. 11, 2025). Theconforming loan limitations for 2026 for Fannie Mae and Freddie Mac home loans. In most of the United States, the 2026 worth for 1-unit homes will be$ 832,750. For areas in which 115% of the regional typical home worth surpasses the standard conforming loan limitation worth, the relevant loan limitation for 1-unit properties will be$ 1,249,125.
Arizona has a brand-new lawsuits funding statute,, effective January 1 2026., reliable January 1, 2026, needs a social media platform to supply a clear and obvious button that enables the user to delete their account and offer the user with the essential steps to erase the user's account and individual information., efficient January 1, 2026, loosens up proof requirements for a rate repairing claim under state law and forbids usage or circulation of a typical prices algorithm as part of a cost repairing scheme.
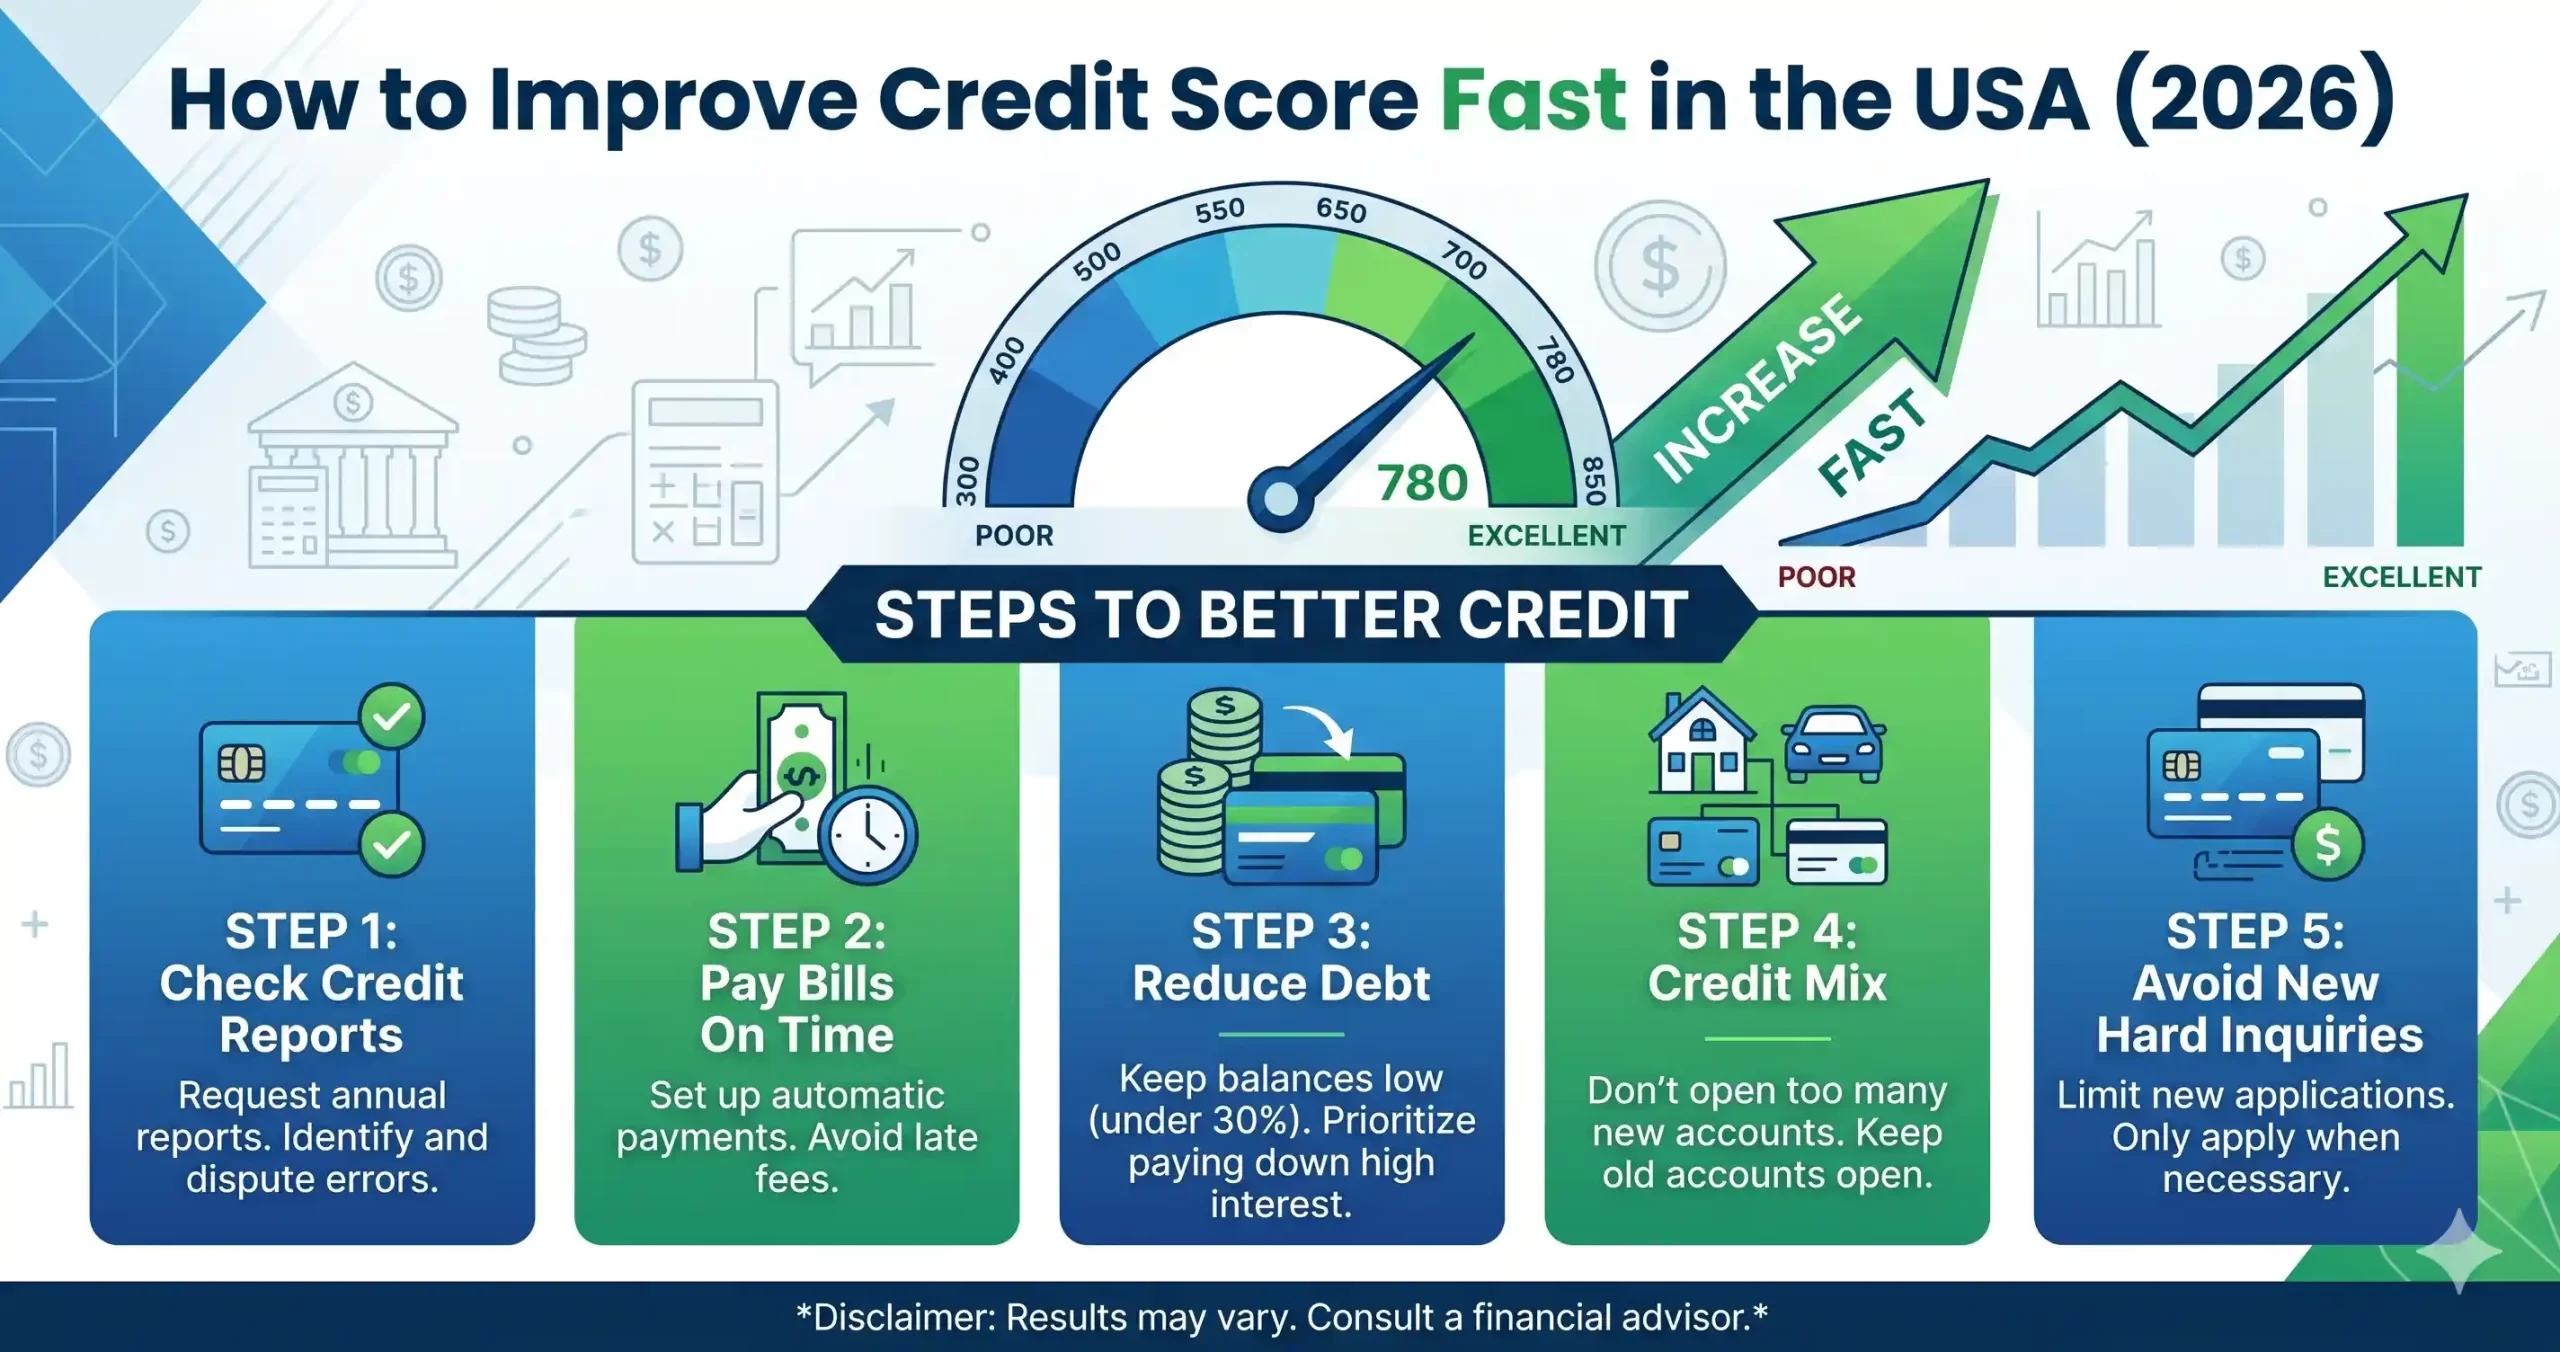
How to Improve Credit Scores Fast in 2026
reliable January 1, 2026, prohibits an accused who established, modified, or used expert system from asserting a defense that the artificial intelligence autonomously triggered the harm to the plaintiff. The food shipment platform need to also supply a client service feature that enables a client to get in touch with a natural person., effective January 1, 2026, prohibits a person from marketing prices for a good, service, or property unless the individual plainly and conspicuously reveals the optimum total of all quantities that a person might pay, although federal government and shipping charges can be left out. A violation is a state UDAP violation. On January 1, 2026, (2024), goes into impact extending Colorado's right to fix laws to certain electronic devices, including cellular phone, computers, and televisions. A producer of digital electronic devices must facilitate the repair work of its devices by offering particular other individuals with the resources required to fix the producer's digital electronic devices. The modifications span almost every short article of the UCC and add a brand-new Article 12 attending to certain kinds of digital possessions specified as "Controllable Electronic Records. "The changes likewise clarify the UCC's applicability to blended deals including both goods and services. The amendments also consist of some various revisions unrelated to technological developments that affect customer deals. See. Thirty-three jurisdictions have actually now adopted the 2022 amendments. Georgia has a brand-new litigation funding statute,, regulating foreign third-party litigation funders that enters into result on January 1, 2026., effective January 1, 2026, supplies different protections for domestic partners whose partner pushes them to take on debt, whether by force or fraud. One piece of precious jewelry approximately$ 5,000 is exempt. Efficient January 1, 2026, offers that when it comes to a customer financial obligation judgment gone into on or after January 1, 2020,$ 1,000 of the$ 4,000 wild card is automatically applied to the judgment debtor's interest in a monitoring or savings deposit account. reliable January 1, 2026, the Indiana data personal privacy statute enters into impact, establishing detailed new information personal privacy requirements.( Might 1, 2023 )., effective January 1, 2026, is a partially industry-sponsored bill that protects made wage payday advance, but includes some consumer defenses, restricting making expedite charges the default choice, or suggesting a default suggestion greater than zero, and likewise needs the service provider, if a customer chooses a no-cost choice, to start the shipmentof the proceeds not behind one company day.( 2024). Beginning January 1, 2026, the base optimum charge is changed annually to the lesser of (1)$ 425, changed by inflation or( 2) the amount resulting from applying a development rate of 3 percent to the changed maximum fee for the previous calendar year. The Louisiana Motor Car Commission will release the adjusted optimum cost on its official website. On January 1, 2026, the maximum loan processing cost on installment loans will change from the current$ 400. See In re, Publication 2024-05-CF (Mich.

Latest Posts
Proven Methods for Fixing Poor Credit Fast
Finding Free Credit Counseling Near Me in 2026
A Guide to Improving Credit in 2026