All Categories
Featured
The Advantages of Free Financial Counseling Programs
Table of Contents
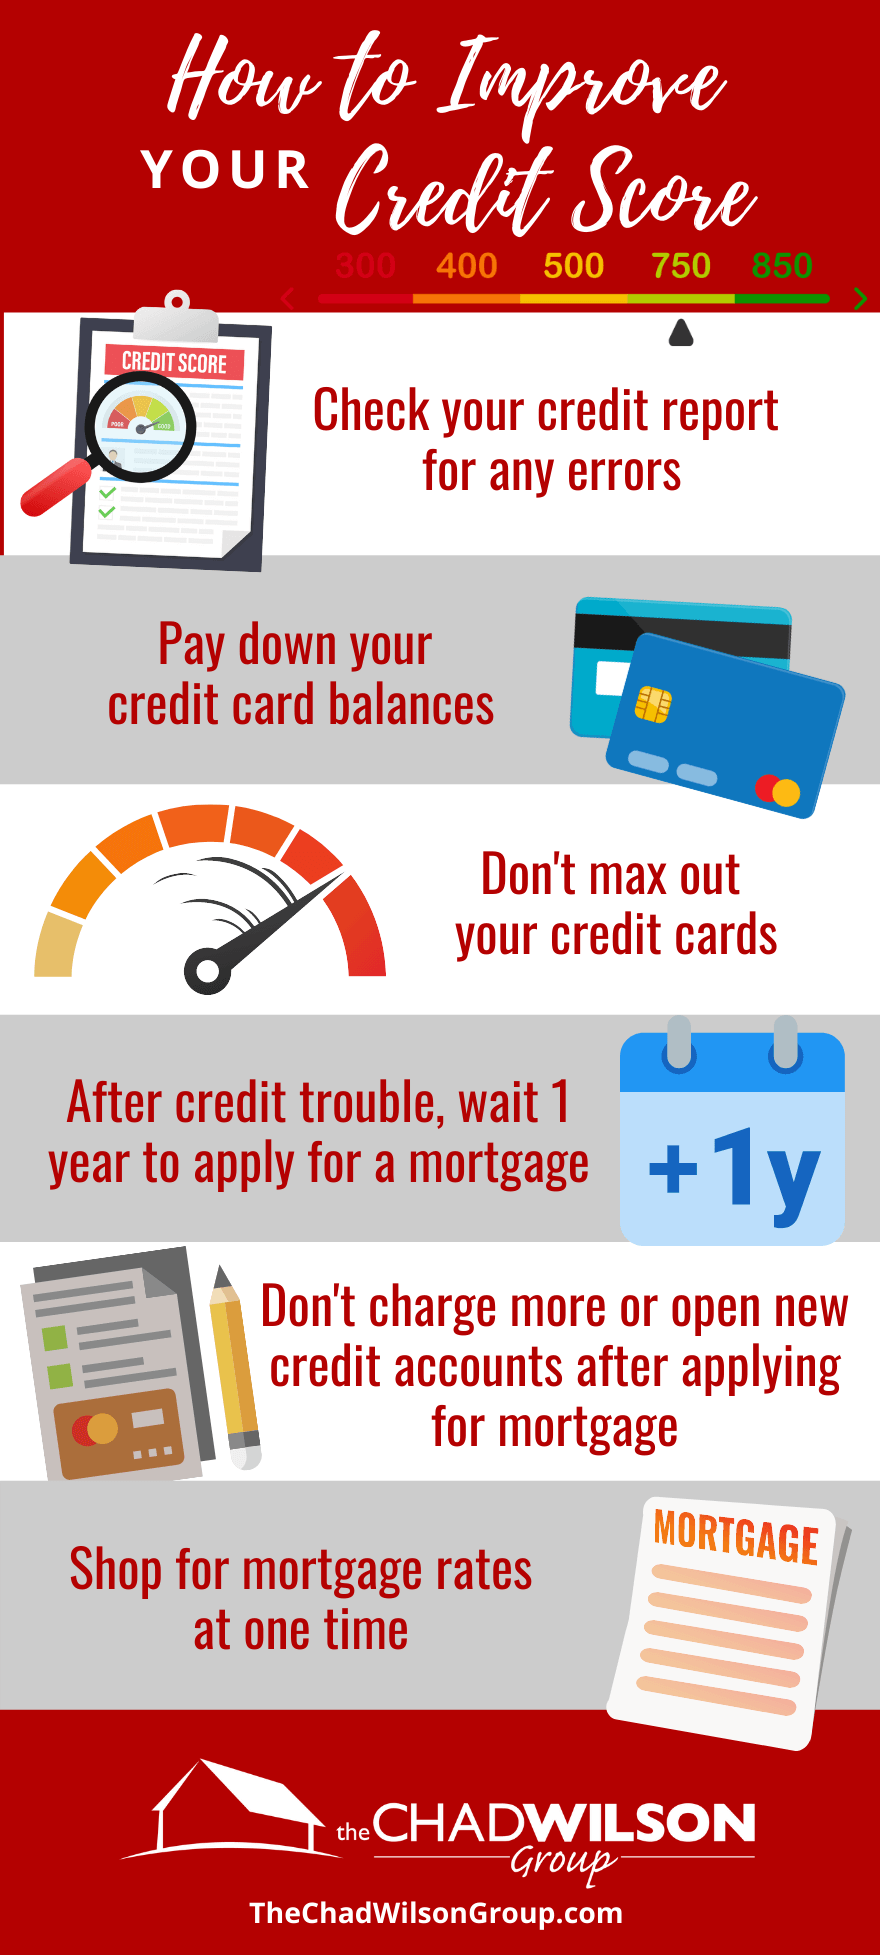
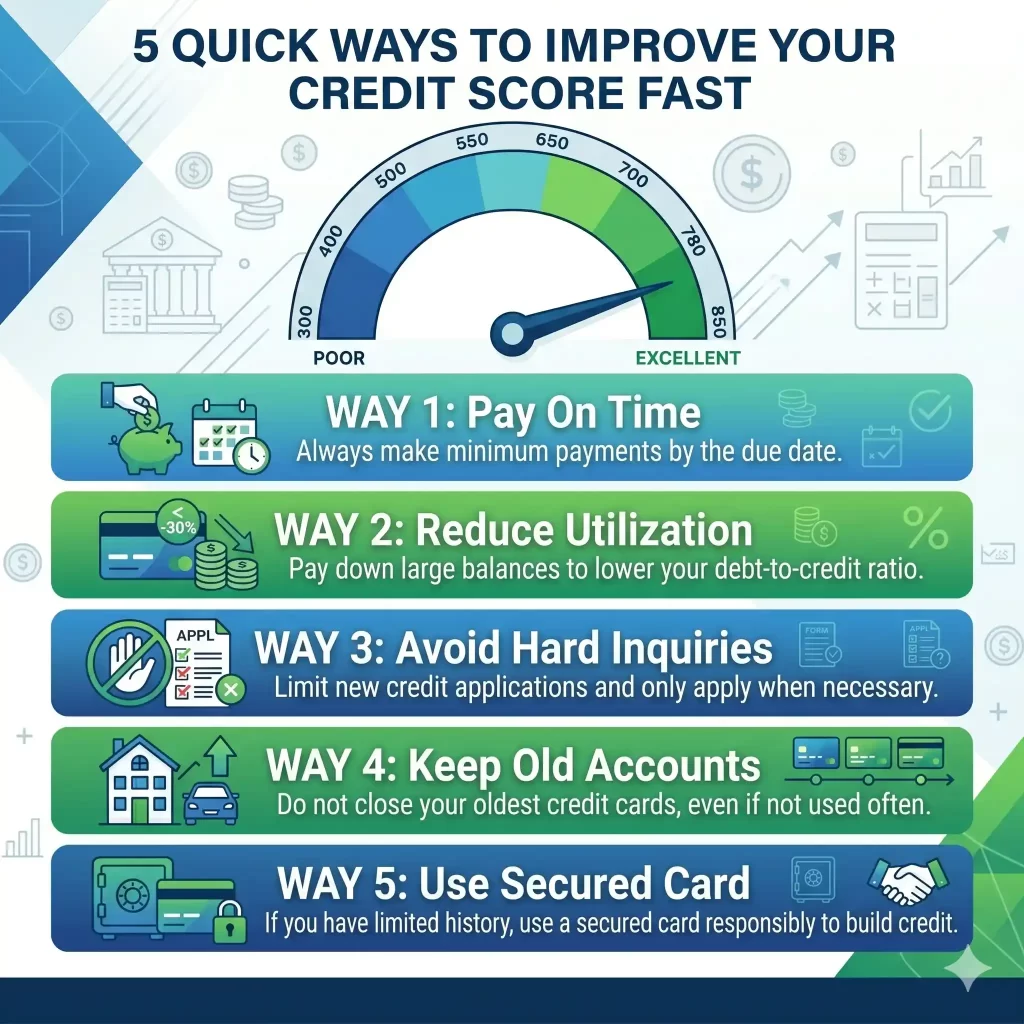
Outcomes vary depending upon the number of missed out on payments you have and how far overdue they are. Missed payments remain on your report for seven years, however their impact fades over time. Your credit utilization ratio, the amount of credit you're using versus what's readily available, accounts for 30% of your FICO Rating and 20% of your VantageScore.
Within a month of your new utilization ratio being reported to the credit bureaus. That card's credit limit and history get factored into your own score.
As a licensed user, the primary cardholder's behavior impacts your credit too. If they miss payments or bring a high balance, it can injure your rating, not just theirs. As soon as the card company reports the brand-new account to the bureaus often within a billing cycle or 2. Once it's authorized and reported, it can decrease your credit usage and boost your credit history.
The secret is to not contribute to those balances. If your income has increased or you have a strong payment history, you're a great candidate for a boost. Ask your issuer whether a tough questions is needed first, as that can momentarily lower your score. Quick once the greater limit is reported to the bureaus, your utilization ratio drops and your rating must follow.
You can likewise dispute the info if it's inaccurate or too old to be listed. FICO 8, the most typically used variation, counts paid and overdue collections on debts of $100 or more. Newer models, FICO 9 and 10, disregard paid collections entirely and treat unpaid medical collections less significantly.
How to Get Free Credit Advice TodayNew Methods to Enhance One's Credit in 2026
Get personalized financial obligation relief solutions that may minimize what you owe and help you restore monetary stability. These cards are backed by a money deposit (generally paid upfront), which functions as your credit limitation. They work like a routine charge card and report your payment history to the bureaus the exact same method, so constant on-time payments construct your score with time.
If you have a thin credit profile, tools like Experian Boost can help you construct it out by, such as rent, energies and streaming services. Not all scoring designs consider this data, but where it's considered, a constant record of on-time payments can meaningfully enhance your rating. As soon as the info is reported to the bureaus.
Closing old accounts reduces your credit history and can increase your credit usage. Combined, this could lower your credit rating.
Closing your earliest account reduces your average account age, increases credit utilization and can decrease your rating when reported to the credit bureaus. It accounts for 10% of your FICO Rating and is not factored into VantageScore at all.
Be careful of taking out new credit simply for the sake of improving your credit. Concentrate on organically blending your credit over time. Fast once the brand-new account is reported to the bureaus, you may see a modification within a billing cycle. See LendingTree's full guide on how your credit rating is determined.
How to Boost Your Credit Score in 2026
The time it takes will depend on the private factors impacting it and the actions you take to alter them. A credit line boost or becoming an authorized user can show outcomes within a billing cycle.
How to Get Free Credit Advice Today
Don't close old accounts, even ones you rarely use. Keep your first credit card active by putting a small repeating charge on it, like a streaming membership, and pay it off each month. Closing old accounts shortens your credit rating and can increase your credit utilization. Combined, this could lower your credit rating.
Closing your earliest account reduces your average account age, increases credit usage and can reduce your score when reported to the credit bureaus. It accounts for 10% of your FICO Rating and is not factored into VantageScore at all.
Watch out for securing new credit just for the sake of improving your credit, nevertheless. Concentrate on organically blending your credit over time. Quick once the new account is reported to the bureaus, you might see a change within a billing cycle. See LendingTree's full guide on how your credit score is determined.
The time it takes will depend on the private elements affecting it and the steps you take to alter them. A credit line increase or ending up being an authorized user can reveal outcomes within a billing cycle.
Comparing Credit Repair Versus Financial Methods
Closing old accounts shortens your credit history and can increase your credit utilization. Combined, this could decrease your credit score.
Closing your earliest account decreases your average account age, increases credit utilization and can decrease your rating when reported to the credit bureaus. It accounts for 10% of your FICO Rating and is not factored into VantageScore at all.
Be wary of taking out brand-new credit just for the sake of improving your credit. Concentrate on naturally blending your credit over time. Fast once the new account is reported to the bureaus, you might see a modification within a billing cycle. See LendingTree's complete guide on how your credit score is computed.
The time it takes will depend on the specific elements affecting it and the steps you take to alter them. A credit line increase or ending up being a licensed user can show results within a billing cycle.

Latest Posts
How to Get Free Financial Counseling Near Me
Key Advantages of Professional Credit Counseling Services
The Advantages of Free Financial Counseling Programs